

If you’re house-hunting in Louisa County in 2026 — whether near Lake Anna’s waterfront along Route 208, around Zion Crossroads off Route 15, or closer to Mineral in zip code 23117 — one of the first questions you’ll face is how to get pre-approved without triggering a hard credit inquiry. The good news: soft-pull pre-qualification is real, it’s available, and it gives you genuine buying power without touching your credit score.
The challenge is knowing which lenders and tools actually use a soft pull versus those that quietly run a hard inquiry the moment you click “submit.” Many large retail lenders begin their online flows with language like “this won’t affect your credit” — then transition to a hard pull once you proceed past initial screening. Buyers should verify the inquiry type at every step.
Here are the top options Louisa County buyers can use right now, ranked by how useful they are specifically for rural Virginia buyers — including those pursuing USDA loans in Louisa’s many eligible zip codes. If you want to explore your options without credit impact first, start with the soft credit mortgage prequalification page at LouisaMortgage.com. Or call Duane Buziak directly at 540-870-5594 for a no-obligation conversation. As an independent mortgage broker (not a direct lender), Duane can shop your file across wholesale lenders to find the program — USDA, FHA, VA, or conventional — that actually fits your situation in today’s market.
1. Louisa Mortgage — Duane Buziak, NMLS #1110647 (NoTouch Credit Pre-Qualification)
Best for: Louisa County buyers who want genuine soft-pull pre-qualification with USDA rural loan expertise
Louisa Mortgage is an independent mortgage brokerage serving Louisa County with a soft-pull-only pre-qualification process built specifically around protecting your credit score during the shopping phase.
Where This Tool Shines
Duane Buziak’s NoTouch Credit process means exactly what it says: no hard inquiry at the pre-qualification stage, period. You get a real rate-and-program picture — including which loan type fits your situation and what your payment range looks like — without any impact to your credit score. That matters when you’re still comparing neighborhoods, weighing Lake Anna waterfront against Zion Crossroads, or deciding whether to move forward at all.
As an independent broker, Duane isn’t limited to a single product shelf the way direct lenders and banks are. He can shop your file across many wholesale lenders to find the program that actually fits your situation. For Louisa County buyers, that includes USDA rural loans — a zero-down option that most out-of-market lenders don’t lead with, even though most of the county qualifies. If you already have a quote from another lender, Duane’s “Dare to Compare” process lets you bring that quote in for a side-by-side comparison with no pressure and no hard pull.
Key Features
NoTouch Credit: Soft pull only at pre-qualification — zero hard inquiry, zero credit score impact during the exploration phase.
Broker independence: Access to many wholesale lenders, meaning your file isn’t limited to one company’s product lineup.
USDA rural loan expertise: Deep familiarity with Louisa County’s eligible zip codes — Mineral, Louisa town center, and much of the Lake Anna corridor — where zero-down USDA financing applies.
Dare to Compare: Bring any existing quote and Duane will run a transparent, side-by-side program comparison before you commit to anything.
Local focus: Duane serves Lake Anna, Zion Crossroads, Mineral, and Louisa town center — not a Richmond or Charlottesville office handling Louisa as an afterthought.
Best For
Louisa County buyers who want to understand their options — USDA, FHA, VA, or conventional — without triggering a hard inquiry. Particularly strong for first-time buyers, USDA-eligible buyers in rural areas of the county, veterans, and anyone who already has a competing quote they want benchmarked honestly.
Pricing
No fee to pre-qualify. Lender fees vary by program and wholesale lender selected. Call 540-870-5594 for a no-obligation consultation. Licensed in VA, FL, TN, GA, DC — NMLS #1110647, Coast2Coast Mortgage LLC NMLS #376205.
2. Rocket Mortgage Pre-Qualification Tool
Best for: Buyers who prefer a fully digital self-service pre-qualification flow available at any hour
Rocket Mortgage is one of the most widely recognized names in digital mortgage lending, offering an online pre-qualification flow that begins with a soft credit pull before transitioning to a full application.
Where This Tool Shines
The Rocket Mortgage pre-qualification experience is fast and genuinely digital-first. You can move through the initial flow at midnight from your phone, get a ballpark rate estimate based on your stated credit range, and understand your general eligibility before speaking to anyone. For buyers who want to do preliminary research independently before engaging a loan officer, that accessibility is real value.
The important caveat: Rocket is a direct lender with a single product shelf. That means your options are limited to what Rocket offers — and for Louisa County buyers specifically, USDA rural program depth is not where large retail lenders typically invest. If your property falls in a USDA-eligible area, you may find more program options through a broker.
Key Features
24/7 digital pre-qualification: Fully online flow available any time — no appointment needed to start.
Soft pull at initial stage: Hard pull is required only when moving to full pre-approval, not during initial pre-qualification.
Rate estimates: Real-time rate estimates based on your entered credit range and loan scenario.
Loan variety: Conventional, FHA, VA, and jumbo loan options available through Rocket’s direct lending platform.
Single-shelf limitation: As a direct lender, Rocket cannot shop your file across wholesale lenders — you get Rocket’s rates only.
Best For
Buyers who want a fast, self-directed digital pre-qualification experience and are comfortable with a large national lender. Less ideal for Louisa County buyers whose top priority is USDA rural loan access or wholesale rate comparison.
Pricing
No fee to pre-qualify online. Origination fees apply at loan closing and vary by loan program and market conditions.
3. Guild Mortgage Pre-Qualification
Best for: Buyers seeking government-backed loan options including FHA, VA, and USDA through a retail lender
Guild Mortgage is a retail direct lender with a broader-than-average range of government-backed loan programs, and their initial pre-qualification uses a soft pull.
Where This Tool Shines
Guild stands out among retail lenders for carrying FHA, VA, and USDA loan products alongside conventional options — which is more program variety than many large direct lenders offer. Their pre-qualification process starts with a soft pull, and they offer both online and in-person application paths, which can be useful for buyers who want a hybrid experience.
That said, Guild is still a single-shelf direct lender. Their USDA program availability may vary by market and loan officer, and unlike an independent broker, they cannot shop your scenario across competing wholesale lenders to find a better rate or lower fees. For Louisa County buyers, it’s worth understanding whether their local coverage includes strong USDA familiarity for Virginia rural areas specifically.
Key Features
Soft pull pre-qualification: Initial pre-qualification stage does not trigger a hard credit inquiry.
Government loan breadth: FHA, VA, USDA, and conventional loan products available through Guild’s retail platform.
Down payment assistance: Some markets have access to down payment assistance programs — eligibility varies by location and income.
Flexible application paths: Online pre-qualification available alongside in-person options depending on local branch presence.
Direct lender structure: Single product shelf — cannot compare rates across wholesale lenders the way a broker can.
Best For
Buyers who want government-backed loan options from a retail lender and prefer working with a company that carries USDA products. Best used as one data point in a broader comparison rather than as a sole source.
Pricing
No fee to pre-qualify. Origination and lender fees apply at closing and vary by loan program.
4. Veterans United Pre-Qualification
Best for: Active-duty military, veterans, and eligible surviving spouses pursuing a VA home loan in Louisa County
Veterans United is a VA loan-specialized direct lender offering a soft-pull pre-qualification designed specifically for military borrowers considering a VA home purchase.
Where This Tool Shines
If you’re a veteran or active-duty service member and a VA loan is your primary path to homeownership in Louisa County, Veterans United has genuine depth in that specific program. Their loan officers focus exclusively on VA loans, which means the guidance you receive during the pre-qualification process reflects real program familiarity — not a generalist reading from a checklist.
The soft-pull pre-qualification flow is available online around the clock, and they assign a dedicated loan officer for follow-up. The meaningful limitation: Veterans United is a single-shelf direct lender focused almost entirely on VA loans. If your situation involves USDA eligibility, down payment assistance layering, or a scenario where VA isn’t the strongest option, their platform won’t surface those alternatives. An independent broker can evaluate VA alongside other programs simultaneously.
Key Features
VA loan specialization: Deep program knowledge, educational resources, and loan officer expertise focused on VA financing.
24/7 online pre-qual: Start the process at any time with dedicated loan officer follow-up after submission.
VA eligibility support: Assistance verifying VA loan eligibility and understanding entitlement before you proceed.
Single-shelf focus: Primarily VA loans — limited ability to compare or pivot to other loan programs if VA isn’t the best fit.
Best For
Veterans, active-duty military, and eligible surviving spouses who are confident VA financing is their path and want a lender with strong VA-specific program knowledge. Veterans who also want to know whether USDA could complement or compete with their VA option should consult a broker.
Pricing
No fee to pre-qualify. VA funding fee and standard closing costs apply at loan closing. VA funding fee amounts vary based on loan type, down payment, and prior VA loan use.
5. USDA Rural Development Eligibility Map
Best for: Any Louisa County buyer who wants to confirm USDA eligibility for a specific property before contacting any lender
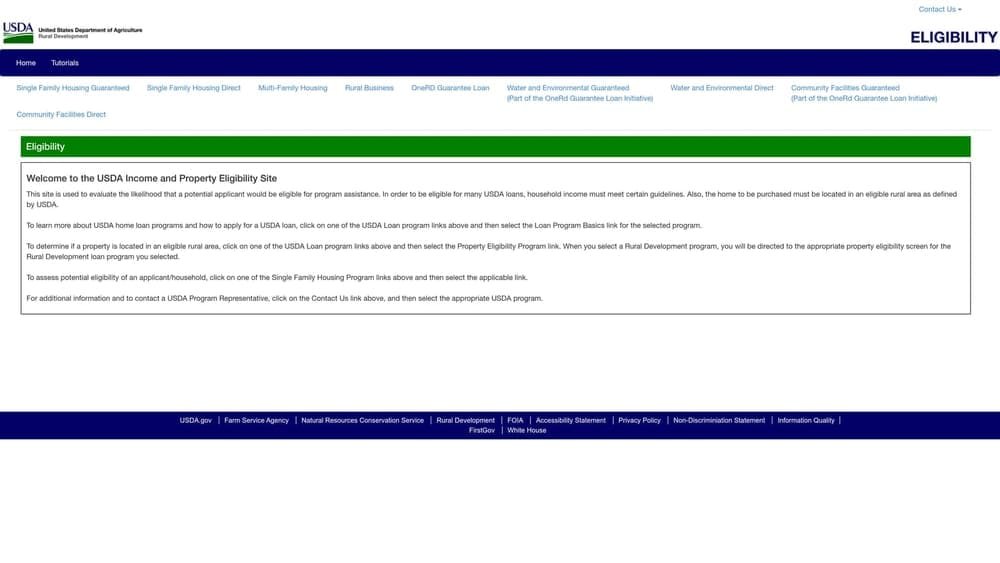
The USDA Rural Development Eligibility Map is a free federal government tool that confirms whether a specific property address falls within a USDA-eligible rural area — with zero credit impact, no login, and no personal information required.
Where This Tool Shines
This is the single most underused tool in the Louisa County homebuyer toolkit. Most of Louisa County — including Mineral, the Louisa town center, and large portions of the Lake Anna corridor — falls within USDA-eligible geography. That means buyers in those areas may qualify for a zero-down mortgage through USDA’s Single Family Housing Guaranteed Loan Program. Confirming eligibility takes about thirty seconds and costs nothing.
The reason this matters so much: many out-of-market lenders don’t proactively surface USDA as an option for Louisa County buyers. If you walk into a conversation with a direct lender without knowing your property qualifies, you may never be offered the program. Checking the map first puts that knowledge in your hands before any lender conversation starts.
Key Features
Free federal government tool: No account, no login, no personal data required at any stage.
Address-level confirmation: Enter a specific property address and get an immediate eligibility result for USDA’s guaranteed loan program.
Zero credit impact: No credit check, no lender contact, no data collection of any kind.
Covers USDA Single Family Housing Guaranteed Loan Program: The primary USDA program used by most Louisa County homebuyers.
Essential first step: Use this before any lender conversation to confirm whether USDA zero-down financing is on the table for your target property.
Best For
Every Louisa County buyer — particularly those considering properties in Mineral, the Louisa town center, or rural areas outside the Zion Crossroads commercial corridor. Check this map before you call any lender. It takes thirty seconds and costs nothing.
Pricing
Free. No cost, no signup, no data required.
6. AnnualCreditReport.com
Best for: Buyers who want to review their full credit picture before any lender sees it — with zero credit score impact
AnnualCreditReport.com is the only federally authorized website for free credit reports, operated under FTC oversight. Pulling your own credit report here is classified as a soft inquiry and has no impact on your credit score.
Where This Tool Shines
Before any lender — soft-pull or otherwise — reviews your credit file, you should see it first. AnnualCreditReport.com gives you access to your full reports from all three major bureaus: Equifax, Experian, and TransUnion. That means you can spot errors, outdated collections, or accounts you didn’t recognize before a loan officer flags them as problems. Cleaning up a reporting error before pre-qualification can meaningfully affect which programs you qualify for and at what rate.
This isn’t a score-monitoring app — it’s the actual raw credit report data that lenders pull from. That makes it more substantive than most free tools. The practical sequence for any Louisa County buyer is: pull your reports here first, review them carefully, dispute any errors you find, then proceed to pre-qualification with a cleaner file.
Key Features
All three bureau reports: Free access to Equifax, Experian, and TransUnion reports in one place.
Soft inquiry only: Pulling your own report is a soft pull — no credit score impact, not visible to lenders.
Error identification: Spot outdated accounts, incorrect balances, or collections before a lender sees them.
Federally mandated access: This is not a third-party aggregator — it’s the government-mandated free access point under the Fair Credit Reporting Act.
Recommended pre-step: Use this before any mortgage pre-qualification conversation to walk in with full knowledge of your file.
Best For
Every homebuyer, without exception. This should be step one before any pre-qualification process — soft-pull or otherwise. It costs nothing, takes minutes, and gives you information that directly affects your mortgage options.
Pricing
Free. Federally mandated at no cost to consumers.
7. Credit Karma
Best for: Buyers who want to monitor their credit score direction during the house-hunting process without any hard inquiries
Credit Karma is a free credit monitoring platform that provides soft-pull score updates and basic financial tracking tools — useful for Louisa County buyers who are in an active search and want to track their score without triggering hard inquiries.
Where This Tool Shines
House-hunting in Louisa County can take weeks or months, especially if you’re watching the Lake Anna waterfront market or waiting for the right property in Zion Crossroads. Credit Karma lets you check your score as often as you want during that period without any credit impact. That’s genuinely useful when you’re trying to understand whether your score is trending up, holding steady, or getting dragged down by utilization or a missed payment.
The important limitation to understand: Credit Karma uses the VantageScore model, not the FICO score that mortgage lenders actually use. Your Credit Karma score may be directionally similar to your FICO score but is rarely identical. Think of it as a useful gauge, not a precise mortgage readiness number. When you’re ready to move forward, a broker like Duane can run a soft-pull pre-qualification that reflects what lenders will actually see.
Key Features
Free soft-pull monitoring: Score updates without hard inquiry — safe to check as frequently as you want.
Score change alerts: Notifications when your score changes or new accounts appear on your report.
Credit utilization tracking: Basic visibility into debt-to-income and utilization ratios that affect mortgage eligibility.
VantageScore model: Score provided is VantageScore, not FICO — mortgage lenders typically use FICO scores, so treat Credit Karma as directional, not definitive.
Free platform: Revenue-supported by financial product recommendations, which you can disregard entirely.
Best For
Buyers who are actively house-hunting and want to monitor their credit trajectory over time without any hard inquiries. Best used as a supplemental awareness tool alongside a full report pull from AnnualCreditReport.com.
Pricing
Free. The platform generates revenue through financial product recommendations that are separate from the core monitoring features.
8. Virginia Housing (VHDA) First-Time Buyer Resources
Best for: Louisa County first-time buyers exploring down payment assistance and state-backed grant programs
Virginia Housing (formerly VHDA) is Virginia’s state housing finance agency, connecting first-time buyers to approved lenders, down payment assistance grants, and homebuyer education — with initial eligibility screening that does not require a hard credit pull.
Where This Tool Shines
For Louisa County buyers who are coming in with limited savings for a down payment, Virginia Housing’s programs can be meaningful. The agency offers state-backed down payment assistance and grant options for income-eligible buyers, and their free homebuyer education courses satisfy the counseling requirements that many lenders impose for first-time buyer programs. Completing that education before pre-qualification puts you ahead of the process rather than scrambling to finish it later.
Virginia Housing doesn’t originate loans directly — they connect buyers to a network of approved participating lenders. That means you’ll still need to work with a lender or broker to access their programs. An independent broker like Duane can help you layer Virginia Housing assistance on top of USDA, FHA, or conventional financing if you qualify — a combination that many single-shelf direct lenders aren’t positioned to structure efficiently.
Key Features
Down payment assistance: State-backed programs for income-eligible Virginia buyers, including grants that don’t require repayment in some cases.
Free homebuyer education: Online courses that satisfy lender counseling requirements at no cost — complete these early.
Soft-pull eligibility screening: Initial informational screening does not trigger a hard credit inquiry.
Approved lender network: Connects buyers to participating lenders — you’ll need a lender or broker to access the actual programs.
Relevant for Louisa County: First-time buyers in the county may qualify for assistance programs based on income and purchase price limits.
Best For
First-time buyers in Louisa County who want to explore down payment assistance options before committing to a lender. Complete the free homebuyer education course early — it’s a requirement for many assistance programs and costs you nothing to finish ahead of time.
Pricing
Free to use resources and education tools. Down payment assistance terms, grant amounts, and income eligibility thresholds vary by program — review current program guidelines at vhda.com or ask a participating lender for details.
Which Option Is Right for Your Situation
Here’s the honest summary: most of the tools on this list are preparation steps. The USDA eligibility map tells you whether zero-down financing is available for your target property. AnnualCreditReport.com shows you what lenders will see before they see it. Credit Karma helps you monitor your score direction during a long search. Virginia Housing points first-time buyers toward assistance programs worth exploring.
None of those tools can actually pre-qualify you for a mortgage. That requires a licensed loan originator who can review your full financial picture, match you to the right program, and give you a real rate and payment estimate. The difference between using a broker and a direct lender at that stage is access: a broker can shop your file across many wholesale lenders to find the best combination of rate, fees, and program fit. A direct lender can only offer what’s on their shelf.
For Louisa County buyers, the recommended sequence is straightforward. First, check the USDA eligibility map for your target property — it takes thirty seconds and costs nothing. Second, pull your credit reports at AnnualCreditReport.com and review them carefully. Third, bring that information to Duane Buziak for a NoTouch Credit pre-qualification: soft pull only, no hard inquiry, no credit score impact, and a clear picture of which programs — USDA, FHA, VA, or conventional — actually fit your situation.
If you already have a quote from another lender, bring it. The Dare to Compare process means Duane will put both options side by side so you can make an informed decision, not a pressured one.
Get pre-qualified today with no credit impact and find out which loan program fits your Louisa County home purchase. Call Duane directly at 540-870-5594 — no obligation, no hard pull, just straight answers about your options.
2 Responses