

A pre-qualification is a quick estimate built on what you tell a mortgage professional, often with a soft credit pull. A pre-approval is a written conditional commitment to lend, backed by a full credit report and verified documents. Sellers on Louisa County and Lake Anna offers give the second one far more weight. This guide is for buyers deciding where to start, and the six options below are compared on credit-pull policy, document requirements, local reach, and how useful the resulting letter is on an offer. Product names, programs, and offices change, so confirm current details with each company as of 2026.
Written by Duane Buziak, NMLS #1110647 | Coast2Coast Mortgage LLC NMLS #376205
Quick Comparison of Pre-Qualification and Pre-Approval Options
- Louisa Mortgage by Duane Buziak: Louisa County and Lake Anna buyers who want a local broker and no hard inquiry at the start; starting price on the website, with fees itemized on the Loan Estimate; pairs a soft-pull pre-qualification with a multi-lender shelf and USDA rural-eligibility focus.
- Rocket: buyers who prefer a self-directed digital process; starting price on the website; a fully online, documents-verified approval option.
- Movement: buyers wanting an in-person officer inside a large national lender; starting price on the website; branch-based officers backed by a national retail platform.
- Alcova: buyers who value a regionally known Virginia name; starting price on the website; a regional Virginia team near the Orange and Lake Anna area (verify).
- Atlantic Coast Mortgage: buyers searching both Charlottesville and Louisa County; starting price on the website; Charlottesville-market presence (verify).
- First Heritage Mortgage: buyers who want a regionally known retail lender to compare against a broker quote; starting price on the website; a team-based process for document collection and letter turnaround.
What Each Letter Proves, and What It Costs Your Credit
A soft inquiry does not affect your credit score and is not seen by other creditors as a new application. A hard inquiry is recorded when you formally apply, and it can lower a score slightly. Pre-qualification usually rests on self-reported income, debts, and assets, and often uses a soft pull. Pre-approval usually means a full credit report (typically a hard inquiry), pay stubs, W-2s or tax returns, and bank statements, and it produces a letter with an expiration date. Scoring models generally treat several mortgage inquiries in a short shopping window as one, but the window length varies by model, so the CFPB’s home-buying resources are worth reading before you apply with more than one company.
Two terms drive both steps. PITI is principal, interest, taxes, and insurance, the full monthly housing payment. DTI (debt-to-income) is your monthly debts, including that payment, divided by gross monthly income.
Here is an illustration, not a quote. Suppose a $350,000 Louisa County purchase with 5% down ($17,500), so a $332,500 loan on a 30-year fixed at an assumed 6.25%. Principal and interest come to about $2,047. Assume property tax at 0.70% of value ($2,450 a year, about $204 a month), homeowners insurance at $1,500 a year ($125 a month), and mortgage insurance at 0.60% of the loan ($1,995 a year, about $166 a month). PITI is about $2,543. With $600 a month in car and card payments and $8,000 in gross monthly income, back-end DTI is $3,143 divided by $8,000, or roughly 39.3%. A pre-qualification would flag that as workable. A pre-approval confirms it against your actual documents. Neither is a loan commitment, and a job change or new debt can undo a letter.
1. Louisa Mortgage by Duane Buziak
Louisa Mortgage by Duane Buziak is an independent mortgage brokerage serving Louisa town, Mineral, Zion Crossroads, and the Lake Anna corridor. It is built for buyers who want to see a number before any hard inquiry hits their credit, then move to a program-matched pre-approval once they are ready to tour.
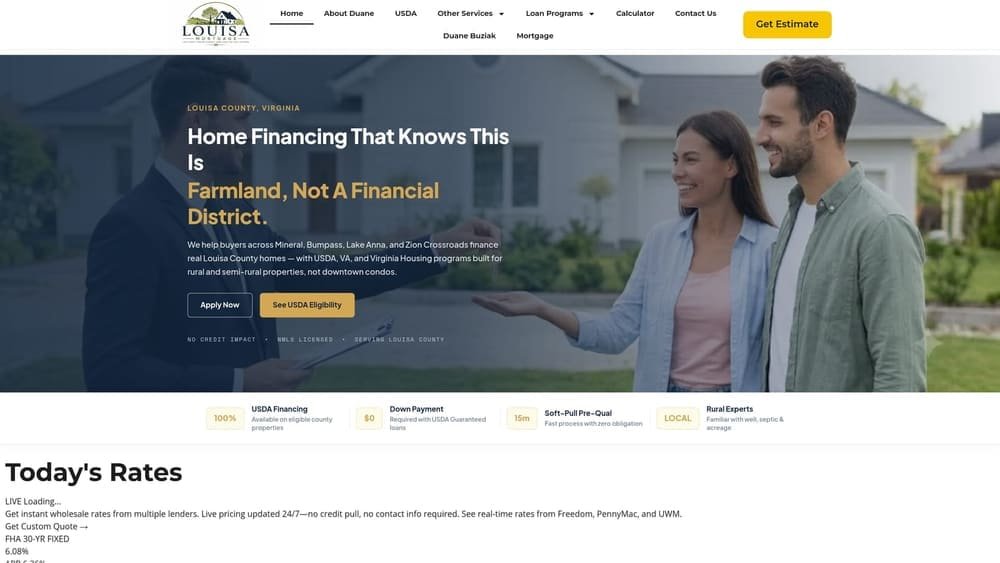
What sets it apart on this list is the sequence. Duane Buziak starts with a soft-pull pre-qualification, then places the file with a wholesale lender whose guidelines fit the borrower, rather than fitting the borrower to one company’s menu. That matters in a county where much of the land may qualify for USDA financing. The USDA eligibility map should be checked address by address, and rural eligibility is a focus here.
- NoTouch Credit soft-pull pre-qualification, so you see a realistic range without a hard inquiry.
- Access to many wholesale lenders as an independent broker, which widens the programs and pricing your file can be matched against.
- USDA, FHA, VA, and conventional purchase and refinance, so one conversation covers every route.
- Dare to Compare review of outside quotes, so you can bring another company’s estimate and see it side by side.
- Lake Anna property questions, such as well and septic and flood zone, raised early so they do not surface after you are under contract.
Setup runs through a secure online application (confirm the current portal), and Duane Buziak coordinates directly with Louisa MLS agents. He is the day-to-day contact.
The limits are plain. This is a broker, not a direct lender, so final underwriting happens at the wholesale partner. Licensing covers VA, FL, TN, GA, and DC only. It is also not an instant-approval app: a documented pre-approval involves a conversation and a document review. Pricing starts at the figure on the website or by calling 540-870-5594. Fees move with loan amount, program, and rate choices, and they appear on your Loan Estimate.
Best for: Louisa County and Lake Anna buyers who want a local broker and no hard inquiry at the start.
2. Rocket
Rocket is a national online direct lender, and its main draw is that the whole process can happen on your phone or laptop without talking to anyone until you want to.
Its distinctive strength on this list is the self-serve, documents-verified approval. You upload pay records and connect accounts, and the platform verifies them digitally, which can produce a stronger letter than a self-reported estimate. Confirm the current name and terms of the verified approval product, since these are revised periodically.
- Online application with document upload, so you can complete a file at night or on weekends.
- A verified approval option that checks income and assets up front, giving sellers more confidence in the letter.
- Purchase and refinance options, so a later refinance can stay with the same company.
- A digital account for tracking progress, which shows which items are outstanding.
Setup is largely self-directed, with digital verification of documents and assets (verify which sources are supported). You run it yourself, with support staff available when something stalls.
The trade-offs come from the model. Rocket is a single-lender shelf, so your file is judged against one set of guidelines and one price sheet. It has no local Louisa presence, which can matter when a listing agent wants to call someone who knows the county. Check whether the programs you need, especially rural ones, are offered and fit your address. Credit-pull timing depends on the product, so ask before you submit whether a hard inquiry will occur.
Starting costs are published on the website. Pricing moves with loan amount, credit profile, down payment, program, and points, and it appears on the Loan Estimate.
Best for: Buyers who prefer a self-directed digital process.
3. Movement
Movement is a national retail lender that pairs a digital application with branch-based loan officers, so it suits buyers who want a person guiding the pre-approval.
Its distinguishing feature here is the officer-led model inside a large platform. You get a named contact, often in a branch, backed by national systems for underwriting and closing. That is a different experience from a purely online process and from a broker who shops multiple wholesale companies.
- Loan-officer-led pre-approval, so someone walks through your income and debts and explains the letter.
- Conventional, FHA, VA, and USDA options (confirm current availability), covering most first-time and move-up scenarios.
- Digital application support, so the paperwork does not have to happen in person.
- A national branch network, which helps if you are relocating into Louisa County from elsewhere.
Setup typically starts with an online portal (verify) and a call with an officer. That officer runs the file day to day, coordinating with processors and underwriters.
The limits: it is a single shelf, so guidelines and pricing come from one company. Experience also varies by individual loan officer, so ask about turnaround times, how the officer communicates, and how often they close in rural Virginia. Ask directly about the credit-pull policy at each step, because pre-qualification practices differ between companies and even between officers.
Starting costs are on the website. Pricing moves with loan size, credit, down payment, program, and points, and final figures are on the Loan Estimate.
Best for: Buyers wanting an in-person officer inside a large national lender.
4. Alcova
Alcova is a Virginia-rooted mortgage lender with regional teams serving Central Virginia. Confirm its current locations, since the sales offices you deal with determine how local the experience feels.
Its edge over the national names on this list is regional familiarity. A team based near Orange and the Lake Anna area (verify) may know local agents, appraisers, and title companies, which helps when a listing agent is deciding how seriously to take your letter.
- A regional Virginia team, so you can talk to people who work in nearby markets.
- Purchase and refinance programs (verify the list), including any government options you may need.
- Familiarity with local agents, which can smooth communication once you are in contract.
- Pre-approval letters for offers, issued after document review.
Setup usually involves an online application (verify) and contact with a regional loan officer or team. Expect a standard document request: recent pay stubs, W-2s or returns, and bank statements.
The main limitation is the one every direct lender shares: one company’s product menu, guidelines, and price sheet. If your situation is unusual, such as self-employment income, a well-and-septic property near the lake, or a rural address you hope to finance with USDA, ask early whether that program is offered and how the credit inquiry is handled at pre-qualification. A regional name also does not guarantee a loan officer based in Louisa County.
Best for: Buyers who value a regionally known Virginia name.
5. Atlantic Coast Mortgage
Atlantic Coast Mortgage is a Virginia-based mortgage lender with a presence in the Charlottesville market (verify current offices). It is most relevant to buyers whose house hunt crosses county lines.
The standout here is the geography. If you are weighing a Charlottesville-area home against something in Louisa town or Zion Crossroads, one company that works both markets can issue a single letter to use across searches, rather than restarting when your target area shifts.
- Virginia-focused lending, so the team deals with state-specific closing practices and local title conventions.
- A Charlottesville-area branch (verify), useful for in-person meetings if you are on the west side of the county.
- Purchase and refinance programs (verify the list), so you can check whether your intended program is available.
- Pre-approval letters for offers, issued after credit and document review.
Setup typically means an online application (verify) followed by a document request. A loan officer or processor handles the file, and you will likely upload the same core documents as elsewhere.
The limits are that it is not based in Louisa County, and it works from a single lender’s guidelines. Someone buying a Lake Anna waterfront property, where flood zone, septic, and appraisal questions can shape financing, should ask how those issues are handled before choosing a program. As with every direct lender here, ask whether pre-qualification involves a hard or soft pull and whether a full pre-approval triggers a hard inquiry.
Best for: Buyers searching both Charlottesville and Louisa County.
6. First Heritage Mortgage
First Heritage Mortgage is a Virginia-headquartered retail mortgage lender that works through loan-officer-led teams (verify current structure).
Its distinct feature among these six is the team model. Instead of one officer juggling every task, a team divides document collection, underwriting follow-up, and letter turnaround. For a buyer who needs a pre-approval quickly before a weekend of showings, that structure can matter.
- A loan-officer team model, so more than one person can chase down missing documents.
- Purchase and refinance programs (verify the list), so you can confirm your intended loan type exists.
- Pre-approval letters, generally issued after credit and document review.
- Virginia market presence, with familiarity with state-specific closing practice.
Setup normally begins with an online application (verify) and contact from a team member. Your job is to supply pay records, tax documents, and bank statements. The team runs the file day to day.
The limitations: guidelines and pricing come from one company. Verify USDA and VA availability before relying on it, since rural-eligible homes near Mineral or the northern part of the county can open a program that a conventional-only conversation would miss. Ask also how pre-qualification is handled and when a hard inquiry is placed, so you are not surprised on your credit report.
Best for: Buyers who want a regionally known retail lender to compare against a broker quote.
Sequencing a Soft Pull, a Verified Letter, and an Outside Quote
Three situations cover most Louisa County and Lake Anna buyers.
- Still deciding on price range or timing: pre-qualify first with a soft pull. Duane Buziak’s NoTouch Credit process shows a realistic range without a hard inquiry, and the USDA eligibility check on your target addresses can change your options.
- Ready to tour: get a documented pre-approval before you walk through a house. A letter backed by verified income and assets carries weight that an estimate does not. Rocket suits a self-serve version, and Movement, Alcova, Atlantic Coast Mortgage, and First Heritage Mortgage suit buyers who want a team or officer involved.
- Comparing offers: bring at least one outside quote to Duane Buziak for a Dare to Compare review, so rate, fees, and program fit are read against the same yardstick.
Ready to take the next step toward your Louisa County home? Get pre-qualified today without any credit impact and discover personalized mortgage options designed for your unique situation, with expert guidance every step of the way. You can also call Duane Buziak at 540-870-5594.